
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.

Amarillo
Tom
Super Poster
VIP Member
Don’t know but @Amarillo still owes me £49. Tom I’ll PM my bank details
Don’t forget to include your mother’s maiden name, PIN code and your eight character password including one upper case letter, one lowercase letter, one number and one special character.

The Tall Luthier
There is no missing pound. It’s false accounting!something to think about on a rainy Sunday.
@Amarillo borrowed £50 from @soulstyledevon and £50 from @GrumpyGranddad to buy a chicken costing £100. After the purchase, he had £3 left.
He returned £1 to @soulstyledevon and £1 to @GrumpyGranddad, and kept £1 for himself.
He now owes £49+£49=£98 plus the £1 he kept for himself, which equals £99….
So where’s the missing £1?
His creditors totalled £98 that’s true. But the pound he kept was a debtor of £1 to his cash account.
You can’t add up creditors and debtors unless you’re called Robert Maxwell.
M
Mansfieldman750
Lifetime VIP Member
We bought our van from Eurovans Crawley in October 2021. Price was £67,281.78. £10,000 from us and the rest from VW Finance.
So we are paying back VW Finance £518.65 per month on PCP at 2.8% with a final balloon payment of £32,374.79 due in October 2026.
Now I see that 5.5% interest is available on a 3 year Cash ISA.
So if my wife and I between us put £27,600 in a risk free Cash ISA sometime before October 2023 this will grow to £32,409.06 by October 2026 which will pay off the van with change left over.
So we will save £4,774.79 on the cost of the van. A reward for saving if you like.
What we had for the last 10 years was a transferrance of wealth from savers to borrowers. It was absurd. Now thrifty savers can get a return on their savings and leveraged borrowers are feeling the pinch.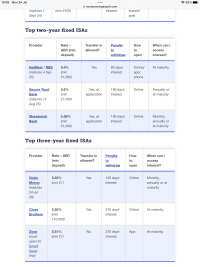 This is a good thing.
So we are paying back VW Finance £518.65 per month on PCP at 2.8% with a final balloon payment of £32,374.79 due in October 2026.
Now I see that 5.5% interest is available on a 3 year Cash ISA.
So if my wife and I between us put £27,600 in a risk free Cash ISA sometime before October 2023 this will grow to £32,409.06 by October 2026 which will pay off the van with change left over.
So we will save £4,774.79 on the cost of the van. A reward for saving if you like.
What we had for the last 10 years was a transferrance of wealth from savers to borrowers. It was absurd. Now thrifty savers can get a return on their savings and leveraged borrowers are feeling the pinch.
This is a good thing.
Amarillo
Tom
Super Poster
VIP Member
I was doing some number crunching today to work out what to do with some money that has come to my two boys indirectly from their great grandmother who died in 2004 some ten years before they were born.
It cannot go into their junior ISA because that is maxed out with sufficient in an investment account to continue maxing it out until they are 18.
So then I looked at junior SIPPs.
It is the first time I have looked in detail at junior SIPPs, and I was surprised at what I found out.
Assuming an average growth of 8.5%:
£240 per month invested into a SIPP between age 10 and maturity at age 57 would give a pension pot of £2 million.
So what about someone born today…
£105 per month between age 0 and age 57 would give the same pension pot - conveniently ignoring the corrosive effect of inflation.
How could a forward thinking 20 year old get a £2m pension pot?
The answer is £557 per month.
And a 25 year old? £858 per month.
So a JSIPP it is for my boys. I’m sure they’ll thank me when they are 57 and I’m either 104 or, more likely, six feet underground.
Can you imagine paying only £240 per month for a £2m pension pot!!??
It cannot go into their junior ISA because that is maxed out with sufficient in an investment account to continue maxing it out until they are 18.
So then I looked at junior SIPPs.
It is the first time I have looked in detail at junior SIPPs, and I was surprised at what I found out.
Assuming an average growth of 8.5%:
£240 per month invested into a SIPP between age 10 and maturity at age 57 would give a pension pot of £2 million.
So what about someone born today…
£105 per month between age 0 and age 57 would give the same pension pot - conveniently ignoring the corrosive effect of inflation.
How could a forward thinking 20 year old get a £2m pension pot?
The answer is £557 per month.
And a 25 year old? £858 per month.
So a JSIPP it is for my boys. I’m sure they’ll thank me when they are 57 and I’m either 104 or, more likely, six feet underground.
Can you imagine paying only £240 per month for a £2m pension pot!!??
G
GrumpyGranddad
Guest User
We opened junior SIPPs with Hargreaves Lansdown for each of our grandchildren when they were born. They’ve done OK.I was doing some number crunching today to work out what to do with some money that has come to my two boys indirectly from their great grandmother who died in 2004 some ten years before they were born.
It cannot go into their junior ISA because that is maxed out with sufficient in an investment account to continue maxing it out until they are 18.
So then I looked at junior SIPPs.
It is the first time I have looked in detail at junior SIPPs, and I was surprised at what I found out.
Assuming an average growth of 8.5%:
£240 per month invested into a SIPP between age 10 and maturity at age 57 would give a pension pot of £2 million.
So what about someone born today…
£105 per month between age 0 and age 57 would give the same pension pot - conveniently ignoring the corrosive effect of inflation.
How could a forward thinking 20 year old get a £2m pension pot?
The answer is £557 per month.
And a 25 year old? £858 per month.
So a JSIPP it is for my boys. I’m sure they’ll thank me when they are 57 and I’m either 104 or, more likely, six feet underground.
Can you imagine paying only £240 per month for a £2m pension pot!!??
Quite obviously the growth will depend on the investment choices.
Amarillo
Tom
Super Poster
VIP Member
We opened junior SIPPs with Hargreaves Lansdown for each of our grandchildren when they were born. They’ve done OK.
Quite obviously the growth will depend on the investment choices.
Fees play a big part too. 1% compounded over 57 years is over 75%.
In the illustration I gave (age 10 to age 57) a one percent per annum charge would reduce the maturity value from over £2m to under £1.5m.
But you are right, investment choices matter too.
I went for low cost trackers.
25% UK
15% Europe ex UK
15% US
15% Japan
15% Pacific ex Japan
15% Em markets
But of course the little tykes might put it all into a perpetual motion technology when they turn 18 and transform it to junk value. Great grandma would turn in her grave.
M
Mansfieldman750
Lifetime VIP Member
I was doing some number crunching today to work out what to do with some money that has come to my two boys indirectly from their great grandmother who died in 2004 some ten years before they were born.
It cannot go into their junior ISA because that is maxed out with sufficient in an investment account to continue maxing it out until they are 18.
So then I looked at junior SIPPs.
It is the first time I have looked in detail at junior SIPPs, and I was surprised at what I found out.
Assuming an average growth of 8.5%:
£240 per month invested into a SIPP between age 10 and maturity at age 57 would give a pension pot of £2 million.
So what about someone born today…
£105 per month between age 0 and age 57 would give the same pension pot - conveniently ignoring the corrosive effect of inflation.
How could a forward thinking 20 year old get a £2m pension pot?
The answer is £557 per month.
And a 25 year old? £858 per month.
So a JSIPP it is for my boys. I’m sure they’ll thank me when they are 57 and I’m either 104 or, more likely, six feet underground.
Can you imagine paying only £240 per month for a £2m pension pot!!??
Yes, it’s a no brainier. Fidelity looks to have the lowest charges by miles.
M
Mansfieldman750
Lifetime VIP Member
So a JSIPP it is for my boys. I’m sure they’ll thank me when they are 57 and I’m either 104 or, more likely, six feet underground.
I believe equities will beat all other asset classes over 30 years or more.
I will be 100 in 30 years time.
Doesn’t matter.
Our “kids” 36 and 33 think same way as me so the timescale is their lifetime not mine.
In the meantime I will keep eating the vegetables to defy the grim reaper.

Amarillo
Tom
Super Poster
VIP Member
I can certainly extol the benefits of finding a good Independent Financial Adviser to assist you unless you're 100% competent in this area.
I have used a financial advisor in May 1990. It was the biggest financial blunder I have ever made. He instructed me to take a low start endowment mortgage - the illustration he gave was for the endowment policy to repay the £40,000 loan in full, leaving me with enough cash left over to “buy yourself a nice new car”.
On maturity the endowment policy was worth £27,000. A shortfall of £13,000.
The thing is, all along my head was telling me that a complicated mortgage arrangement must surely be more expensive than a simple repayment mortgage. But I was young (23) and clearly gullible.
I’ll do my own research and leave it to others to pay for financial advisors’ flashy cars.
Amarillo
Tom
Super Poster
VIP Member
@Amarillo Where do you get the 8.5% number from…?
FTSE all world index 1993 to 2023 is 9.3% pa average.
8.5% is a reasonable expectation over the long term. 5% growth plus 3.5% dividends reinvested. But nothing more than a guess.
$100 invested in the S&P 500 on 1 January 1929 (before the Wall Street Crash) would be worth over $500,000 now. 9.56% pa.
S&P 500 Returns since 1929
 www.officialdata.org
B
Barry Chuckle
With that logic you could say that also applies to all accountants too.The job of a financial advisor is not to make money for you. It’s to make money from you.
Amarillo
Tom
Super Poster
VIP Member
Don’t forget that alcoholIn the meantime I will keep eating the vegetables to defy the grim reaper.
 is an excellent preservative.
B
Barry Chuckle
Isn't hops also one of your 5 fruit and veg!?Don’t forget that alcoholis an excellent preservative.
M
Mansfieldman750
Lifetime VIP Member
With that logic you could say that also applies to all accountants too.
Well, Amarillo pretty much said it all. Pound cost averaging in a low cost index tracker and stay the course. That should do the trick. Charges matter.
No IFA is going to tell you that but it’s the best course of action for the majority of investors.
There are plenty of good books to read before paying an IFA.
Stocks for the Long Run by Jeremy Siegel
Common sense on Mutual Funds by Jack Bogle.
Warren Buffet’s annual letter to shareholders.
Many more. Invest a few quid in finding out what you don’t know. If you don’t end up going down the route Amarillo recommends, read them again.
M
Mansfieldman750
Lifetime VIP Member
Don’t forget that alcohol
Oh yes, plenty of that too.
Amarillo
Tom
Super Poster
VIP Member
With that logic you could say that also applies to all accountants too.
I shun them too.
If an accountant costs £1000 + VAT, they must find me savings of at least £1200 to be value for money.
B
Barry Chuckle
Good point, but sadly I wouldn't know where to start filing my accounts to Companies House so I pay the fees for peace of mind too!I shun them too.
If an accountant costs £1000 + VAT, they must find me savings of at least £1200 to be value for money.
Amarillo
Tom
Super Poster
VIP Member
Good point, but sadly I wouldn't know where to start filing my accounts to Companies House so I pay the fees for peace of mind too!
The same principle applies to financial advice. If the total cost - including any commission to the IFA and additional trading costs comes to 1%, the advice given must beat the market by 1%. But… if you take fund managers as a whole and average them out… they track the market.
So the best option for the amateur investor is to pay 0.06% ongoing plus 0.02% one off transaction fee on a low cost tracker fund. (0.06% compounded over 57 years is under 3.5%.)

Last edited:
Amarillo
Tom
Super Poster
VIP Member
I have a financial advisor who charges 0.6%.
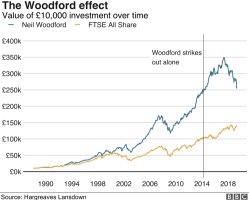
He removed a large chunk of my pension from Woodford a couple of months before it tanked. I was very grateful. 1998 to 2017 was pretty good.
View attachment 115375
0.6% won’t be the end of it. All those funds your FA invests your money into will have their own charges, and those funds might be investing in other funds… and so on. The price you are paying is not opaque.
That is not to say that there aren’t good fund managers. But as FMs, on average, track the market, there will be as many bad FMs as there are good FMs, and success as a FM is largely down to luck rather than judgement.
However, it is essential for there to be FMs for trackers to track the average of all FMs.

Lambeth Cali
Super Poster
VIP Member
I agree that the 700% Woodford went up from 1998 to 2017 is pre fees.0.6% won’t be the end of it. All those funds your FA invests your money into will have their own charges, and those funds might be investing in other funds… and so on. The price you are paying is not opaque.
That is not to say that there aren’t good fund managers. But as FMs, on average, track the market, there will be as many bad FMs as there are good FMs, and success as a FM is largely down to luck rather than judgement.
However, it is essential for there to be FMs for trackers to track the average of all FMs.
I calculate how I’m doing by how much is in my pension. That’s completely opaque as it’s post fees.
I can understand most people’s scepticism about Financial Advisors but mine has averaged 9% post fees which seems good for 0.6%pa.
Your 8.5% seems a little optimistic from trackers.
Btw my current pension saving goes 100% into a US tracker. The US is considerably more energy self sufficient than the EU and UK so while Vladimir is camped out in Ukraine they are expected to do better.
Last edited:
Similar threads


- Replies
- 42
- Views
- 14K

VW California Club




About us
The VW California Club is the worlds largest resource for all owners and enthusiasts of VW California campervans.